Posted in Guest Authors

A Guide to Creating Reliable Retirement Income Without Relying on Pensions

Many retirees living on a fixed budget know the uneasy math of retirement: bills arrive on schedule, but income doesn’t always. Pension reliance risks show up when payouts change, costs rise, or benefits don’t stretch as far as expected, and those retiree income challenges can feel surprisingly personal after decades of working. At the same time, investment income variability can turn what looked steady on paper into a month-to-month guessing game. The goal is simple: retirement income stability built through thoughtful income diversification for retirees.

Understanding Diversified Income Streams

At its core, diversified income means you are not betting your monthly comfort on one paycheck replacement. You spread your cash flow across a few different sources so a hit to one does not knock over your whole plan. It is also a realistic mindset, since diversification cannot assure, protect against loss, but it can reduce how much any single surprise hurts.

This matters because retirement is long, and life gets lumpy. A repair, a medical bill, or a price jump feels different when you have more than one way to cover it. It also closes the planning gap when only 32% say they’re good at setting up and sticking to a long-term financial strategy.

Think of it like a small table with several legs instead of one pillar. If one leg wobbles, the table still stands. A modest side income can keep groceries covered while you adjust the rest.

One alternative some retirees consider is a life settlement, starting with the basics and reputable buyers.

Turn an Unneeded Life Policy Into Cash Flow: Life Settlements

Once you’re thinking in terms of multiple income sources, it helps to look at assets you may be paying for but no longer truly need.

One often-overlooked option for some eligible retirees is a life settlement, selling an existing life insurance policy to a third party for a lump-sum payment. That cash can be redirected to support long-term financial stability and help diversify your income sources, especially if the policy no longer fits your goals.

Of course, this is a trade-off. When you sell the policy, you’re giving up the death benefit your beneficiaries would have received, so it’s worth weighing that loss carefully and getting professional guidance before moving forward.

If you decide to explore it, working with a life-settlement broker can make the process far easier to navigate. A broker who represents policyowners as a fiduciary manages the entire life settlement process, shops your policy to multiple buyers to seek competitive offers, charges no upfront fees, and only earns a commission if the transaction closes, while allowing you to cancel at any time. To get a sense of the marketplace, you can start by reviewing companies that buy life insurance policies.

Next, we’ll shift from this single, high-impact option to several practical ways to generate income from things you already own.

Try 6 Practical Ways to Monetize What You Already Own

When I think about “extra retirement income,” I don’t start with a brand-new business idea, I start by asking, what am I already paying for, maintaining, or sitting on that could pay me back? With so many households at risk of not having enough retirement income, small, steady wins can matter just as much as big financial moves.

  1. Turn a spare room into light rental property income: If being a full-time landlord sounds exhausting, start smaller: rent out one room to a traveling professional or a local student for a semester. Keep it low-drama by using a simple written agreement, setting “quiet hours,” and requiring a security deposit. The goal is predictable cash flow that helps cover fixed costs like property taxes and utilities, without taking on a second mortgage or major renovation.
  2. Make your home work harder with storage or parking rentals: Before you rent living space, consider renting “non-living” space, driveway parking, garage storage, or a shed. It’s often simpler (fewer tenant issues) and can still create a reliable monthly payment. A practical first step is a 30-minute walk-through: measure the space, decide what you’ll clear out, and set rules on access times and what can’t be stored.
  3. Start part-time consulting income from your last job description: Your experience has a market, especially if you can solve a specific problem in 2–4 hours. Write a one-page “services menu” based on what you used to do: training a replacement, reviewing a process, creating templates, or being a short-term project coach. Keep the work retirement-friendly by offering fixed packages (for example, two 90-minute calls plus a written summary) rather than open-ended hourly help.
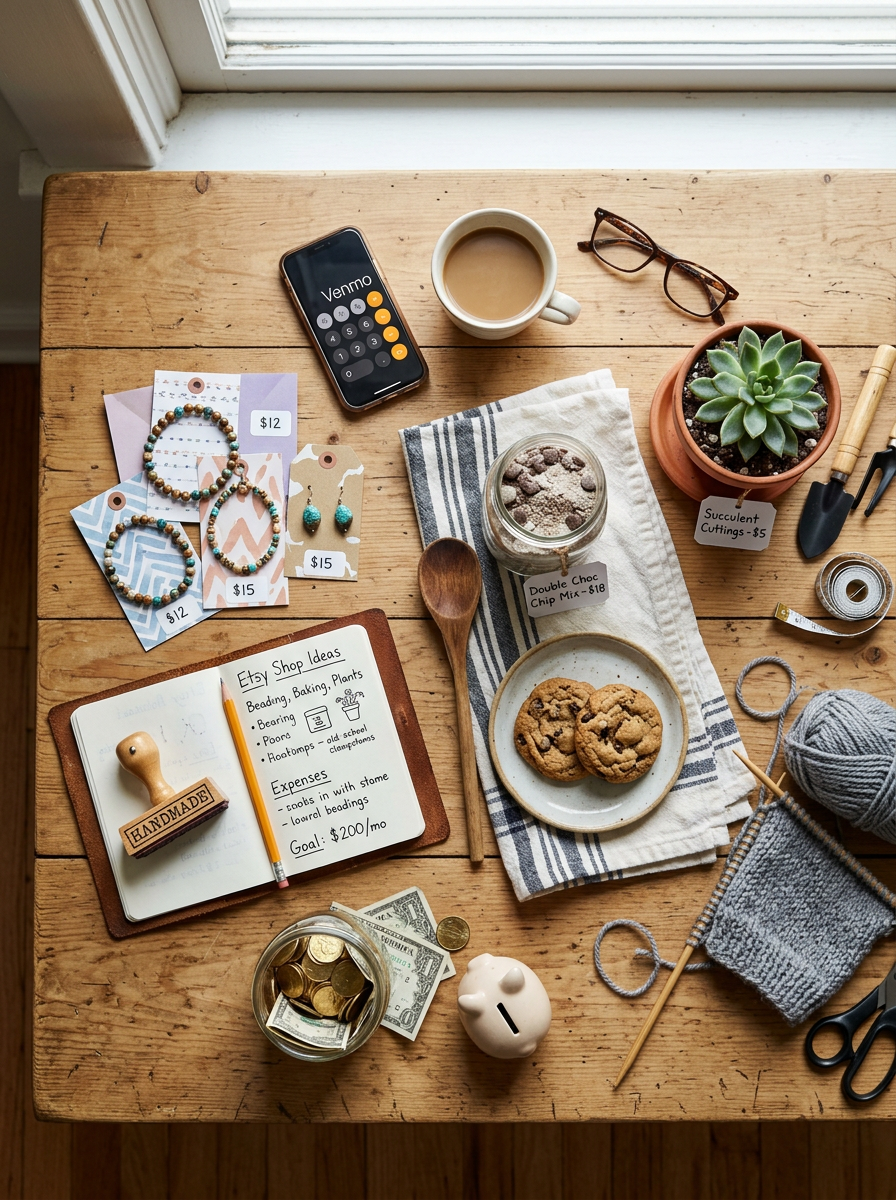
  4. Build a tiny retirement side business around what you already buy: The best side businesses in retirement often piggyback on existing routines: baking for a weekly community group, basic handyman tasks, pet sitting, or sewing repairs. Start with a two-week pilot and a waiting list instead of saying yes to everyone. Pricing trick that keeps it sustainable: charge enough that you’d still do it on a “tired week,” and cap your weekly hours.
  5. Use asset liquidity strategies before you sell something big: If you’re sitting on valuables, tools, collectibles, a second vehicle, test the market by renting or consigning before selling. Renting keeps the option to reclaim the item later, while consigning can reduce your workload. Treat it like a mini project: list 10 items, pick 3 to monetize this month, and track what actually brings in money versus headaches.
  6. Coordinate “cash unlock” moves with your bigger plan: If you’re considering something like a life settlement, pair it with smaller income streams so you’re not relying on a single decision to carry your budget. I like to separate money into buckets, monthly basics, annual surprises, and “opportunity cash”, so any new income has a job. That structure also helps you sanity-check fees, taxes, and timing before you commit.

Stacking two or three of these ideas can create steady breathing room, and make it much easier to judge which income options are truly worth the effort.

Retirement Income FAQs

A few practical answers to the questions I hear most.

Q: What if I don’t want a “job” in retirement, just a little extra cash flow?
A: That is a smart boundary, not a weakness. Choose low-lift options like renting a parking spot, listing storage space, or offering one fixed consulting package per month. Set a weekly time cap first, then pick the income idea that fits inside it.

Q: How do I know if I’m hurting myself by tapping assets too soon?
A: Start by separating “spendable now” from “long-term.” A planner can help you apply sustainable withdrawal research so withdrawals stay aligned with a 30-year horizon. If you are DIY, run a conservative budget and stress-test it with higher costs.

Q: Can alternative income streams mess up my taxes or benefits?
A: They can change your tax picture, so keep records from day one and set aside a percentage of each payment. If you receive means-tested benefits, ask the agency how earnings and rental income are treated before you scale up.

Q: What if I need liquidity and don’t want to sell something valuable yet?
A: Try “reversible” moves first: rent the item, consign it, or offer it seasonally. You can also set a decision date, like 90 days, to evaluate hassle versus profit before committing to a sale.

Q: Should I feel uneasy relying on rent or side income instead of investments?
A: A little caution is healthy, and diversification is the point. Aim for two or three small sources so a single vacancy or slow month does not derail you. If you want reassurance, the breadth of responses in the 2026 RCS reflects how common it is to mix income sources.

Small, steady steps can buy real peace of mind and more choices each month.

Choose One Income Diversification Move to Boost Retirement Resilience

Retirement can feel tight when pensions don’t stretch like they used to and investment income swings at the wrong time. The steadier path is an empowered financial planning mindset that leans on income diversification benefits recap: spread your income sources so no single one has to carry the whole load. When that approach is in place, day-to-day decisions get calmer and retirement income resilience becomes something you can actually feel. Diversified income turns retirement from a guess into a plan. Pick one practical retirement income step this week, review your current income sources and choose one small, actionable financial next step to strengthen the weakest spot. That kind of steady attention supports stability not just for your budget, but for your peace of mind, too.

Posted in Guest Authors

A Senior’s Guide to Keeping Memories Without the Clutter

You’ve held onto a lot over the years, some of it tucked in drawers, some framed on the wall, and some living quietly in boxes you haven’t opened in a while. Every item has a story, a person, a place behind it. But keeping all of it can start to feel heavy, especially when your space and energy are focused on today. The good news? You don’t have to give up meaningful memories to live with less. You just need ways to keep the feeling without keeping all the stuff. This guide offers simple, clutter-free ways for seniors to preserve what matters most—with heart, not hassle.

Digital Memory Backup

Memories live in stories and snapshots, but they don’t need to take up your closet. If you’re looking to keep photos without clutter, the best move is to scan or digitize your collection and then follow the 3‑2‑1 photo backup rule. That means keeping three copies of each file, using two different media types, and storing at least one of those off-site—like in a cloud or external drive tucked in a family member’s home. It’s a set‑and‑forget move that adds real peace of mind. You’re not risking fading prints or forgotten folders anymore. Once uploaded, you can access memories from anywhere without digging through boxes.

Minimalist Memory Rituals

Some things you just can’t throw out. But you also don’t want them weighing down your living space. That’s where ritual helps. Before you let go of an object that holds emotional weight, take photos of keepsakes before releasing them. Whether it’s a handmade gift, a concert ticket, or a kitchen tool your kid used to play with, capture it. Write down a memory tied to it if you want to. Then let the object go. The power isn’t in the item, it’s in the connection you’ve preserved.

Memory Collage Crafting

Some memories are too rich for a drawer and too important to scatter. That’s where a simple collage comes in. Pick a handful of photos that matter: a moment that shaped you, a person who steadied you, a place you still dream about. Arrange them together in one image, one page, one quiet tribute that holds more weight than clutter ever could. You can print it or keep it digital, frame it or save it to a screen, but it’s yours. A memory collage doesn’t just preserve, it curates, filters, and lifts what matters into focus.

Digital Picture Frames

You shouldn’t have to choose which memories get wall space. Instead, choose a frame that auto‑rotates images. Set it once and let it do the remembering for you. These digital frames loop through dozens—or even hundreds—of your favorite photos, quietly keeping them in your daily life. There’s no need to print, frame, and hang every single shot. You simply upload, hit play, and let the slideshow do its work. Birthdays, grandbabies, anniversaries, vacations—all of it, gently rotating without demanding space or dusting.

Digital Album Platforms

Sometimes what’s overwhelming isn’t the stuff, it’s the software. If that’s been your hold-up, skip the complicated options and pick platforms with intuitive features. Look for simple menus, large fonts, easy photo grouping, and, if you need it, voice commands. Once you’re in, the key is maintenance: make it a weekly routine to sit down and remove duplicates, blurry shots, or anything that no longer hits you in the heart. That’s how a digital album stays personal instead of bloated. A few favorites per month? That’s enough to build a timeline that actually means something.

Photo Calendars

It’s one thing to keep memories, it’s another to see them every day. One of the simplest, most space‑saving ways to do that is to create a calendar. Think of it as a living memory loop: Each month features a new photo, a fresh story, a new feeling. The best part? It replaces bulk with rhythm. All it takes is a few clicks. Choose a template, upload your photos, and personalize with text or stickers if you like. The final product gets mailed to you, ready to hang. One slim item, twelve quiet joys.

Choosing the Right System

Before you dive into any of these ideas, pause. Ask yourself what kind of system you’ll return to; what doesn’t just sound good but feels possible. Forget what works for your neighbor or what you saw online. You have to pick a system that you’ll use. That means knowing your habits. Are you likely to scan and upload weekly? Or would you rather print a set of photos once a year? Whatever the answer, build around it. Memory‑keeping only matters if you’re engaged with it.


Minimalism isn’t about erasing, it’s about distilling. It’s not about having less sentiment but giving each memory the space it deserves. Whether you back up your photos in the cloud, craft collages, or cycle through images on a digital frame, your stories remain yours—visible, alive, and unburdened by stuff. You can hold on to everything that matters without holding onto everything. Choose rituals that resonate, tools that fit, and rhythms you’ll keep. That’s how memories last, not by clinging, but by curating. And in that quiet clarity, the best parts of your life find room to breathe.

Posted in Guest Authors

Affordable Vacation Homes: Smart Strategies for Retirees

Finding an affordable vacation home for your retirement can be both exciting and daunting. With the right strategies, you can secure a home that not only fits your budget but also enhances your golden years. From evaluating the cost of living to understanding tax benefits, each step is crucial in making a wise investment.

Evaluate the Cost of Living

When planning to purchase a vacation home, it’s essential to assess the cost of living in potential locations to ensure it aligns with your financial goals. For instance, living in a smaller city might be more budget-friendly compared to a bustling metropolis where expenses are notably higher. By using a cost of living calculator, you can effectively compare these costs and determine if your income will stretch further in your chosen destination. This careful analysis aids in budgeting and ensures your retirement funds are used wisely, allowing you to enjoy your new home without financial stress.

Assess Area Growth

When planning to purchase a vacation home for your retirement, it’s essential to consider the area’s economic potential to ensure your investment grows over time. Focus on regions with promising economic trends such as job growth and infrastructure improvements, which often lead to increased property values. For example, areas benefiting from advancements in technology or enhanced transportation networks can offer significant appreciation potential. By understanding these factors, you can secure a vacation home that not only provides immediate enjoyment but also promises long-term financial benefits.

Safeguard Your Home with a Home Warranty

As you explore options for your retirement retreat, consider the value of investing in a home warranty. This proactive step protects you from unexpected repair costs, covering essential systems like heating, cooling, electrical, and plumbing. Unlike manufacturer warranties, home warranties provide broader coverage, including major appliances such as dishwashers and washing machines. By choosing this option, you gain peace of mind and financial security, enabling you to fully enjoy your retirement retreat. If you’re curious about how a home warranty can make a difference, check this out to explore options for safeguarding your new home and avoiding unforeseen expenses.

Explore Shared Ownership

For retirees seeking an affordable vacation home, exploring shared ownership models like timeshares or fractional ownership can be a smart strategy. Timeshares often have a lower initial cost, but they come with ongoing fees that can rise over time. In contrast, fractional ownership usually requires a higher upfront investment but offers more predictable expenses, making it easier to budget. Additionally, fractional ownership provides a deeded interest in the property, allowing you to potentially benefit from property appreciation.

Understand the Tax Benefits for Vacation Homes

When planning to purchase a vacation home, it’s essential to understand how the IRS classifies personal versus rental use, as this can significantly impact your tax obligations and benefits. If you rent out your vacation home for less than 15 days a year, the IRS does not consider it a rental property, allowing you to exclude this income from your taxable income. However, you can only deduct property taxes and mortgage interest, not other expenses. This makes it crucial to meticulously track and document how you use your vacation home throughout the year.

Navigate Seasonal Price Fluctuations

When you’re considering buying a vacation home, it’s important to recognize how seasonal tourism can impact both prices and availability. During peak vacation months, popular destinations often see a surge in demand, which can drive up property prices significantly. This trend is echoed in other tourist-heavy areas. As a retiree seeking an affordable vacation home, consider timing your purchase during off-peak seasons.

Choose to Renovate or Buy New

When considering whether to renovate an older vacation home or purchase a new one, it’s important to weigh the financial and practical aspects of each option. Renovating an older home can be a cost-effective choice if the structure is solid and only needs updates to align with modern standards. This approach allows you to add value by incorporating modern amenities and improving energy efficiency, often at a lower cost than building new. On the other hand, buying a newer home offers the advantage of lower maintenance costs and fewer unexpected repairs, making it a potentially more predictable investment.

Finding the perfect vacation home for your retirement is a journey that combines financial savvy with personal aspirations. By carefully considering factors like cost of living, market trends, and ownership models, you can secure a property that not only meets your budget but also enriches your retirement experience. With thoughtful planning, your ideal retreat is well within reach, offering both comfort and financial peace.

Discover your next favorite series with Reluctant Retiree Book Reviews, where sweet romances and thrilling adventures await your reading pleasure!

Posted in Guest Authors

Returning to the Classroom: A Guide for Retirees Considering Further Education

Retirement offers a unique opportunity to pursue goals that may have been on hold during your career. For many, returning to school tops the list – whether to explore a new passion, gain skills for a post-retirement career, or simply stay mentally active. However, diving back into education requires thoughtful planning. From financial considerations to lifestyle adjustments, taking the time to evaluate your options ensures that your academic journey is both rewarding and manageable.

Balancing Education Costs in Retirement

Before diving into educational pursuits, it’s crucial to evaluate how these expenses will impact your financial stability. With Social Security benefits seeing only modest increases, it’s important to ensure that your savings and income can support additional educational costs. Carefully reviewing your retirement budget will help you make informed decisions about pursuing further education without compromising your financial health.

Navigating Online Education

One of the most appealing aspects of pursuing an online degree during retirement is the flexibility it offers. For instance, if you’re interested in exploring psychology degree online options, you can study the cognitive and affective processes that drive human behavior at your own pace. Online programs are typically more affordable than traditional in-person classes, and they eliminate the need for commuting, allowing you to balance learning with other retirement activities seamlessly.

Exploring Different Educational Paths

When considering a return to education, it’s important to explore programs specifically designed for retirees. Many institutions offer flexible schedules and online courses, making it easier to fit learning into your lifestyle. These programs often focus on lifelong learning and personal enrichment, allowing retirees to sharpen their skills while connecting with peers who share similar goals and values.

Enhancing Retirement Through Campus Engagement

Returning to school isn’t just about academics; it’s also a chance to expand your social network. By participating in campus activities such as clubs, sports, or volunteer groups, you can meet like-minded individuals and foster a sense of community. This social engagement can significantly enhance your educational journey and contribute to personal growth and happiness. Engaging in these activities can be a cost-effective way to explore new interests and skills, making your retirement years more rewarding.

Improving Cognitive Health Through Lifelong Learning

Engaging in educational activities during retirement can be a powerful way to boost cognitive health. The mental stimulation provided by structured learning can help slow cognitive decline – a common concern in later years. By pursuing education, you not only enrich your knowledge but also strengthen your mental faculties, ensuring a more vibrant and fulfilling retirement.

Creating an Effective Study Plan

To make the most of your educational pursuits, it’s essential to design a study schedule that complements your lifestyle. Start by assessing your daily routines to identify when you’re most alert and focused. Use a calendar app to organize your obligations, ensuring your study sessions don’t clash with other activities. Incorporating regular breaks is crucial to maintaining mental clarity and avoiding burnout. By treating your study time with the same importance as any other commitment, you can foster accountability and motivation.

Going back to school in retirement is more than just an academic pursuit – it’s also a golden opportunity to enrich your life and embrace new challenges. By carefully considering your goals, resources, and support systems, you can set yourself up for success in this exciting venture. Take the time to explore your options, stay informed through continuous learning, and remember that the joy of discovery has no age limit.

Discover your next favorite book series with Reluctant Retiree Book Reviews, where passionate readers find captivating stories and unforgettable characters!